
You like a business, but the price feels high. Or it feels low, and you wonder what the catch is.
Knowing how to find valuation of a stock helps you answer one question. Is the price fair for what the business earns and may earn?
If valuation feels like guesswork, you are not alone. So, take it one step at a time, and the picture gets clearer.
Here, all numbers are hypothetical, for illustration only.
What Does Valuation of a Stock Mean?
First, get the idea clear before the formulas. In fact, everything else on this page builds on it.
Valuation is an estimate of what a business is worth, compared with the price the market asks today.
It is not one number. Instead, it is a range built from several methods, and every method rests on assumptions.
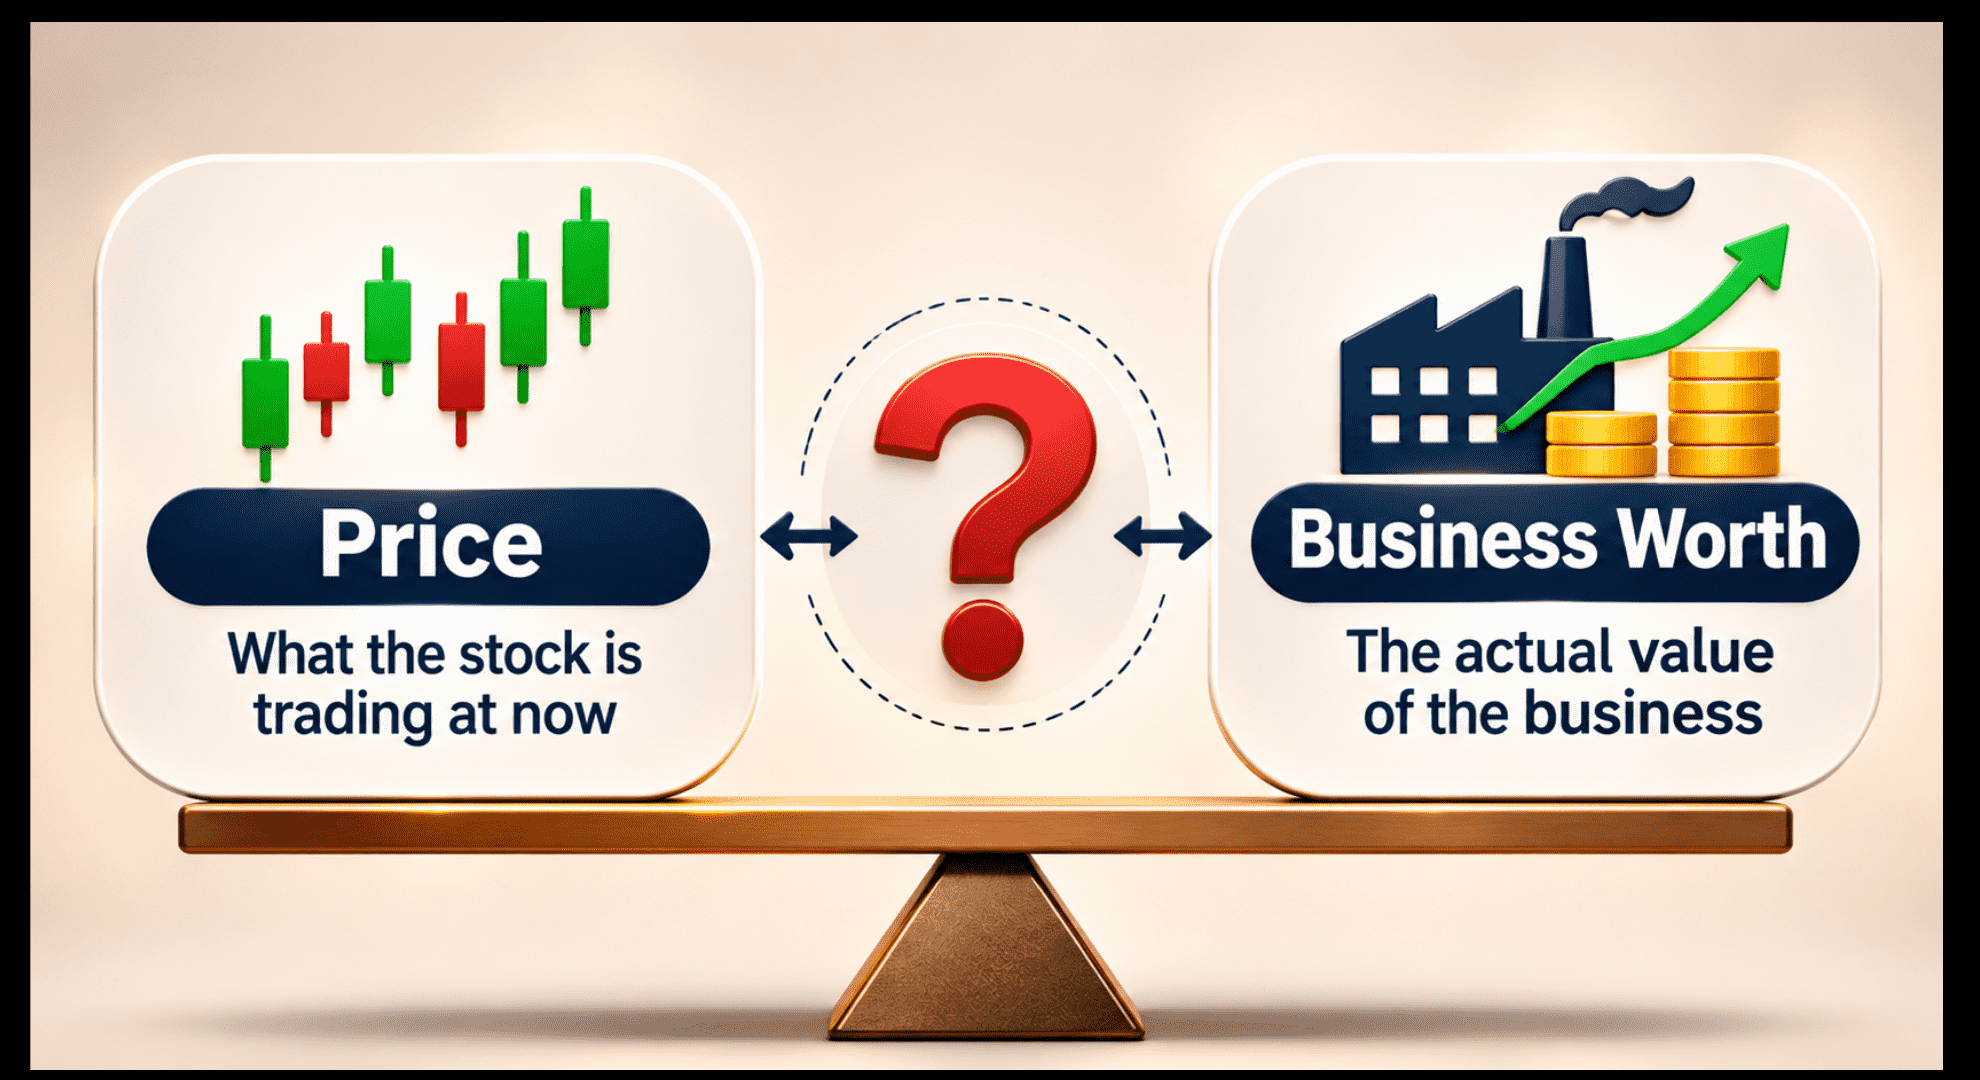
A low price does not make a stock cheap. Likewise, a high price does not make it expensive. The business behind the price decides that.
How to Value a Stock Step by Step: 5 Simple Methods
Valuation has many methods, so the order matters. First come ratios, then peers, cash flow, assets and sector.
Step 1: How to Find Valuation of a Stock With Relative Ratios (P/E, P/B, PEG)
In short, relative valuation compares the price with something the business produces. The table below gives one short formula for each common ratio.
| Ratio | Formula | What it asks |
|---|---|---|
| P/E | Price per share / earnings per share | How much do I pay for Rs 1 of profit? |
| P/B | Price per share / book value per share | How much do I pay for Rs 1 of net assets? |
| EV/EBITDA | (Market cap + debt – cash) / EBITDA | What is the whole business priced at, debt included? |
| PEG | P/E / expected annual earnings growth (%) | Is the P/E justified by growth? |
However, each ratio shows only one angle. So, use two or three together, not one alone.
For a deeper look at growth-adjusted pricing, read how the PEG ratio is calculated and which growth number to use. Also, different sources use different growth estimates, so their PEG figures may not match.
Step 2: Compare With Peers and the Company’s Own History
In fact, a ratio alone means little. For example, a P/E of 20 can be rich for one sector and modest for another.
So place the number next to similar companies and next to the same company’s past years.
The table below compares three hypothetical companies of similar size. All values are for illustration only. Market cap = price x shares; PEG uses the stated growth rate.
| Item | Company A | Company B | Company C |
|---|---|---|---|
| Price per share (Rs) | 300 | 400 | 180 |
| EPS (Rs) | 15 | 16 | 12 |
| Book value per share (Rs) | 100 | 80 | 90 |
| Expected earnings growth (%) | 15 | 8 | 12 |
| P/E | 20.0 | 25.0 | 15.0 |
| P/B | 3.0 | 5.0 | 2.0 |
| EV/EBITDA | 6.2 | 8.0 | 6.0 |
| PEG | 1.33 | 3.12 | 1.25 |
Notice that Company B looks priciest on every measure, and its growth is the lowest. That mismatch is worth questioning.
Meanwhile, Company C looks cheapest. But a low ratio alone cannot tell you whether it is cheap or simply weaker.
Now check Company A against its own past. If its P/E has mostly stayed within a band over several years, today’s reading means more than a single number.
Step 3: How to Find Valuation of a Stock With Absolute Valuation (DCF)
In contrast, absolute valuation ignores peers. It asks what the business’s future cash is worth today.
The discounted cash flow (DCF) idea works in five plain steps:
- Estimate the cash the business can generate each year (free cash flow).
- Choose a growth rate for the next few years.
- Choose a long-term growth rate for the years after that.
- Pick a discount rate, which reflects risk and the return you expect.
- Bring all future cash back to today’s value and add it up.
Here, free cash flow is the cash left after the business pays for its assets. You can learn how to work it out in this free cash flow explainer.
Now the caution. DCF looks precise, but it is only as good as its inputs.
The table below uses a hypothetical business with free cash flow of Rs 100 crore. It has a five-year forecast and a terminal stage. Values are for illustration only and are not a price target.
| Case | Growth (5 yrs) | Discount rate | Terminal growth | Estimated value (Rs crore) | Change vs base |
|---|---|---|---|---|---|
| Base | 10% | 12% | 4% | 1,662 | 0.0% |
| Higher discount rate | 10% | 13% | 4% | 1,472 | -11.4% |
| Slower growth | 8% | 12% | 3% | 1,403 | -15.6% |
| Higher terminal growth | 10% | 12% | 5% | 1,845 | +11.0% |
Notice that a one-point change in a single input moves the answer by double digits. In the base case, about 71% of the value sits in the terminal stage.
So treat a DCF result as a range of outcomes, not a fact. Small assumptions carry big weight.
Step 4: Look at the Asset-Based View
The asset-based view asks what the business owns minus what it owes. Book value per share is the simplest form of it.
It suits businesses that hold many physical or financial assets. In contrast, it suits asset-light businesses far less, since their worth sits in brands, software or people.
Book value also depends on accounting choices. Therefore, use it as a cross-check, not as the final answer.
Value investors lean on this view often. Next, learn value investing to see how they combine it with earnings.
Step 5: Adjust for Sector Differences
Sectors carry different norms for growth, debt and capital needs. So the same ratio means different things in different places.
Here is how the common ratios tend to fit different business types in general:
- Asset-heavy and financial businesses are often read with P/B.
- Businesses with large debt are better compared on EV/EBITDA than on P/E.
- Fast-growing businesses are often read with PEG and cash flow.
- Cyclical businesses show unstable earnings, so their P/E can mislead at peaks and troughs.
Finally, compare a company with its own sector, not with the whole market.
How to Know if a Stock Is Overvalued
No single signal proves it. But a few questions bring you closer to a sensible view.
Is the price high against peers and against its own history, while growth is lower? Does the DCF only work with very optimistic inputs?
If most answers point the same way, the stock may be overvalued. However, if they disagree, treat the result as unclear and keep studying.
This is where the idea of a safety cushion matters. The margin of safety concept explains why investors want a gap between their estimate and the price. After all, estimates can be wrong.
Common Mistakes When You Value a Stock
Most valuation errors come from habit, not from maths. So, watch for these:
- Calling a low P/E cheap. A low ratio may signal weak growth or hidden problems. This is the classic value trap.
- Using one ratio only. Each ratio hides something that another can reveal.
- Ignoring debt. Two companies with the same P/E can carry very different debt loads.
- Trusting forecasts too much. Growth numbers are estimates, and past growth does not guarantee future growth.
- Comparing across sectors. A bank and a software firm are priced on different logic.
Quality matters as much as price. A DuPont analysis of ROE shows whether returns come from margins, efficiency or borrowing.
A Simple Stock Valuation Checklist
Run through this list for any company you study. It keeps your work organised and your emotions out of the way.
- Write down what the business does and how it earns.
- Note P/E, P/B, EV/EBITDA and PEG for the company.
- Pick three to five true peers and compare the same ratios.
- Check the company’s own multi-year range for the same ratios.
- Look at debt, cash flow and earnings quality.
- Try a simple DCF with a base, a low and a high case.
- Read the gap between price and your range, and keep a cushion for error.
- Write the reasons down, so you can review them later.
Valuation gives you a way to think, not a signal to act. Also, your mentor or a trusted reviewer can help you check your reasoning before you rely on it.
If you are new to this style of thinking, the basics of value investing are a good place to begin.
Where to Find the Data You Need to Value a Stock
Companies publish results and shareholding details every quarter, and annual reports carry fuller statements. First, look on the company’s investor-relations page and on stock exchange filings.
Also, check the format and timelines on the exchange website, since rules can change. To build the habit, learn fundamental analysis alongside valuation.
Do you also compare P/E and PEG and still wonder whether a price is really fair?
Reading about ratios is easy, but valuing real companies with a mentor’s review builds a method you trust.
Join our live classes from your mobile, ask your doubts and learn step by step.
Conclusion
So, valuation is a range built from several methods, not one number. Start with relative ratios, compare peers, test a DCF, check assets and adjust for the sector.
In short, treat every result as an estimate that rests on assumptions. As a result, you avoid calling a stock cheap or expensive from one ratio.
Finally, write down your reasons and keep a cushion for error. Remember, this is learning, not a buy or sell signal.
Disclaimer: This page is for education only and is not investment advice. All figures are hypothetical, shown for illustration only.
Valuation uses estimates that can be wrong, and past growth does not guarantee future growth. Do your own research or speak to a SEBI-registered adviser.
Frequently Asked Questions
Before investing capital, invest your time in learning Stock Market.
Fill in the basic details below and a callback will be arranged for more information: